HDB resale · Singapore
Buying an Older HDB Flat: What 58 Years of Lease Means for You
By Jim Tan · Rules and sources checked 7 November 2026
Yes, you may buy an older HDB flat with 58 years left if you meet HDB’s purchase conditions. Your financing needs a closer look. CPF usage and the HDB loan limit depend partly on whether the lease covers the relevant youngest buyer to age 95. A buyer aged 35 plus a 58-year lease reaches age 93, so the age-95 coverage test is not met. Check your usable CPF and approved loan before setting an offer budget. CPF Board’s shorter-lease guidance · HDB’s financing comparison
When I assess an older HDB flat with a buyer, I put the floor plan, the remaining lease and the available funds side by side. A home can suit your daily routine and still need more cash than you expected. Here is how I would work through those decisions.
Buying an older HDB flat with 58 years left: the age-95 check
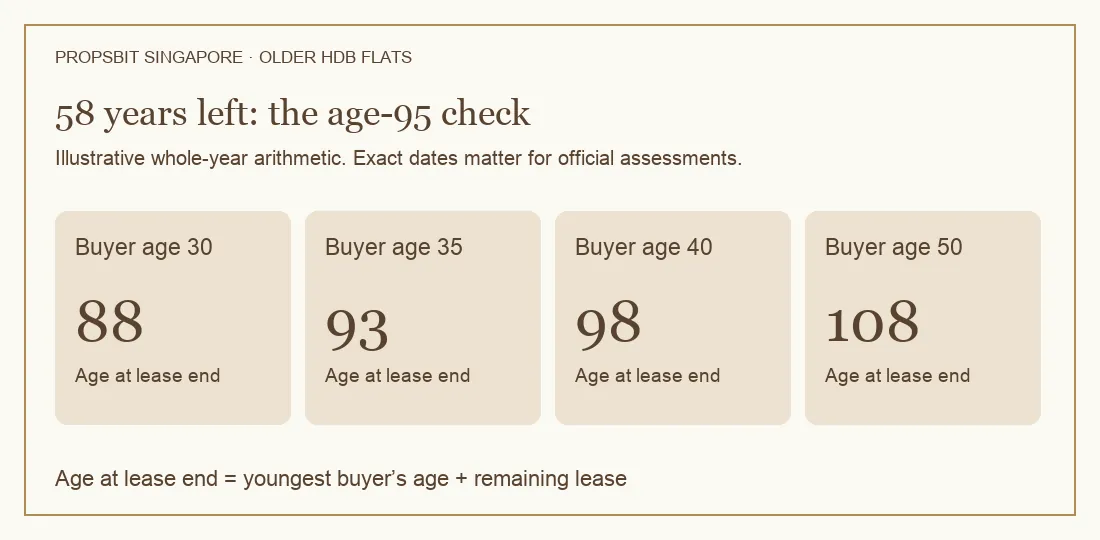
Start with the actual remaining lease at the relevant application date. Do not infer it from the year the block was built. For a first check, add the buyer’s age to the remaining lease. The examples below use whole years for clarity. HDB and CPF use the actual dates and their own assessment rules.
| Illustrative youngest buyer age | Remaining lease | Age at lease expiry | Reaches age 95? |
|---|---|---|---|
| 30 | 58 years | 88 | No |
| 35 | 58 years | 93 | No |
| 40 | 58 years | 98 | Yes |
| 50 | 58 years | 108 | Yes |
Age at lease expiry = buyer’s age + remaining lease. In whole-year arithmetic, age 37 plus 58 reaches 95. Confirm the exact dates rather than treating your next birthday as a financing decision. Passing this coverage test alone does not establish the amount you can borrow or the CPF balance available to you.
How much CPF can you use for an older HDB flat?
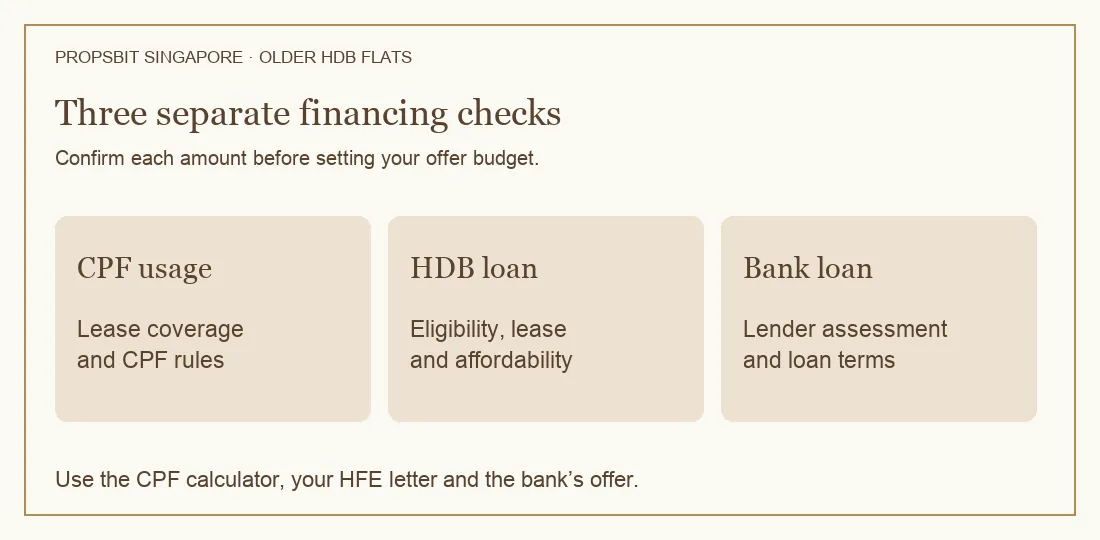
If the lease does not cover the youngest relevant owner to age 95, CPF usage may be prorated. CPF Board directs buyers to its Housing Usage Calculator to find the permitted amount. Enter your ages, the actual lease and the purchase details. Use the output alongside your available Ordinary Account balance, because an allowed limit is different from money already in your account. CPF Board’s explanation · CPF Housing Usage Calculator
If the lease covers the youngest owner to age 95, ordinary CPF housing limits still apply. The lower of the purchase price and valuation is relevant, and additional conditions can apply when CPF usage reaches a limit or when you own another property. A 58-year lease is not a rule that allows every buyer to use the same amount. CPF Board’s housing usage overview
Can you get an HDB loan or a bank loan for an older HDB flat?
HDB loan. An eligible buyer’s loan-to-value limit is prorated from the applicable maximum of 75% when the lease does not cover the youngest applicant to age 95. Eligibility, income, repayment period and affordability also affect the offer. Obtain a valid HFE letter before the seller grants you an Option to Purchase. HDB loan and bank loan comparison · HDB’s purchase process
Bank loan. Ask the lender to assess the specific older HDB flat. Banks can have restrictions for shorter leases, and your age, existing debts and repayment period matter. Do not carry an HDB loan estimate over to a bank application. If using a bank loan, HDB requires a valid bank Letter of Offer before you exercise the Option to Purchase. HDB’s financing comparison · HDB’s Option to Purchase guidance
What cash budget should you prepare?
I would calculate two amounts. First, the part of the flat price that the approved loan and usable CPF will not cover. Second, the stamp duty, legal fees, renovation, moving and other costs you must fund. Keep a buffer for the home itself, especially when you are considering replacing older fittings.
Illustrative purchase-price balance = S$700,000 flat price − S$450,000 approved loan − S$170,000 usable CPF = S$80,000. These are invented budgeting inputs, not a loan or CPF estimate for a 58-year lease. Applicable duties, fees and renovation costs are additional. Any cash-over-valuation is already part of the purchase-price balance and must not be counted twice.
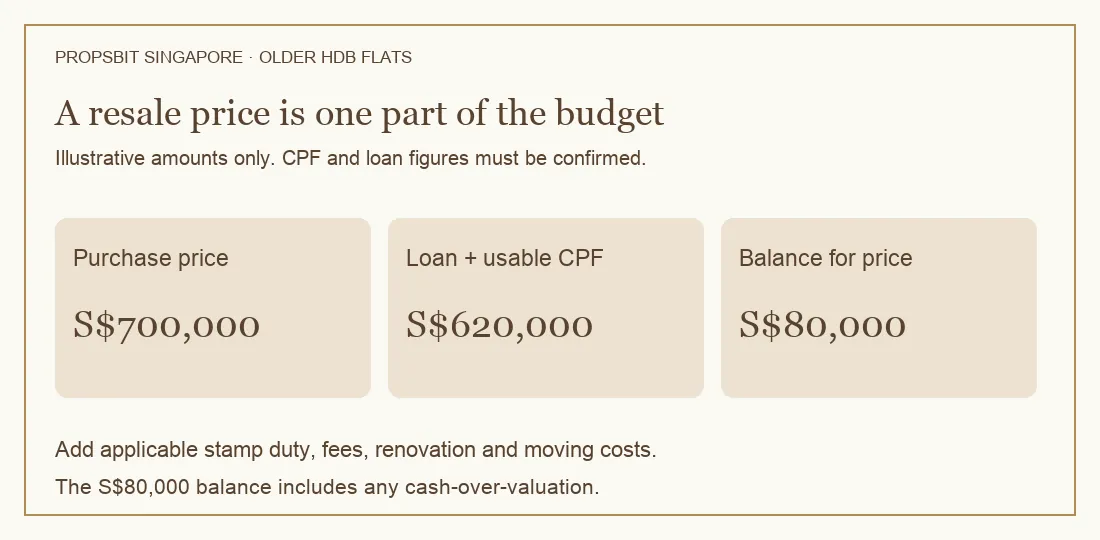
For example, if the agreed price is S$700,000 and the valuation is S$680,000, the S$20,000 difference forms part of the cash needed for the price. Check the remaining cash payment requirements with your lender or HDB. A Request for Value is required when using CPF or housing finance, subject to HDB’s procedure. HDB’s financing guide · HDB Request for Value
Two older HDB flat examples in Bishan
These four-room transactions show why I would compare actual homes. I verified the records against data.gov.sg on 7 November 2026. Remaining lease below is the figure recorded at the transaction, so it should not be treated as the exact lease today.
| Block | Sale month | Area and floor range | Price | Recorded remaining lease |
|---|---|---|---|---|
| 113 Bishan Street 12 | October 2026 | 104 sq m · 10–12 | S$860,000 | 58 years 4 months |
| 115 Bishan Street 12 | August 2026 | 104 sq m · 4–6 | S$836,000 | 58 years 6 months |
Both records show lease commencement in 1986. They sold in different months and floor ranges, and the records do not describe the renovation or exact outlook. I would shortlist Block 113 for a higher-floor viewing and assess Block 115 if access towards Bishan MRT and Junction 8 matters. At both viewings, check noise with the windows open. The S$24,000 difference between these two sales does not establish a block premium. HDB resale dataset
Start with the Block 113 Bishan Street 12 guide and Block 115 Bishan Street 12 guide. You can also compare Block 112, Block 114 and Block 116 through the Bishan HDB Insights hub.
What happens when you want to sell later?
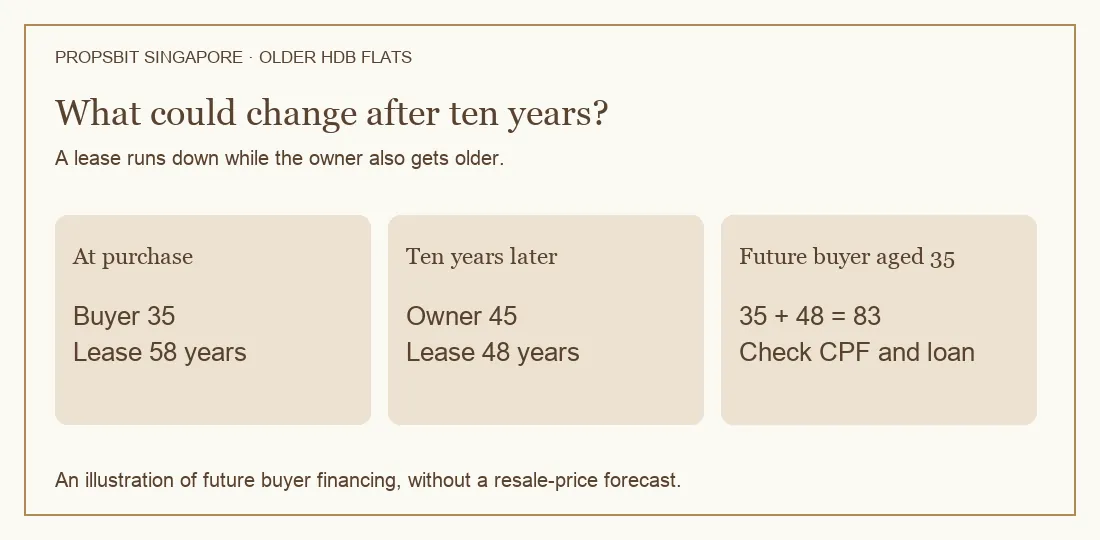
Consider the next buyer’s financing as part of your own housing plan. A flat with exactly 58 years left today would have about 48 years left after ten years. A buyer aged 35 at that later purchase would reach age 83 at lease expiry. That future buyer may need to work within shorter-lease CPF and lending limits.
Your own age rises while the lease runs down. A 35-year-old who buys the flat would be 45 ten years later, but the next buyer may be much younger. I would test the move against your intended time in the home, retirement plans and ability to fund a future replacement. This example describes lease arithmetic and financing questions, without predicting resale demand or price.
What I would inspect before buying an older HDB flat
- Rooms and daily use. Measure your furniture, check circulation and walk the lift-to-door route. Compare usable space rather than judging the home from its recorded area alone.
- Condition and work needed. Inspect for signs of leaks, worn fittings and repairs. Get a suitable contractor’s assessment and quotations before assigning a renovation allowance.
- HIP status and bills. Verify what work was completed for the block and flat, and whether any upgrading charges are pending. HDB says the owner at the date of billing pays the upgrading cost. HDB’s HIP guide
- Lease and redevelopment status. Check the remaining lease independently. HDB’s published SERS guidance says there are currently no plans for more SERS projects. I would assess the purchase on the existing lease and confirmed facts. HDB’s current SERS guidance
Frequently asked questions about buying an older HDB flat
Is an older HDB flat with less than 60 years left eligible for CPF?
It can be, subject to CPF’s conditions. CPF usage depends partly on whether the remaining lease covers the youngest relevant owner to age 95. Where it falls short, the permitted amount may be prorated. Check the actual property and household inputs in the official calculator. CPF Housing Usage Calculator
Does a buyer aged 40 automatically get the maximum loan for a 58-year lease?
No. The whole-year sum of 40 and 58 reaches 98, so it passes the age-95 coverage check in this illustration. The actual loan still depends on eligibility, affordability, repayment period and the lender’s assessment. The approved amount can be lower than the maximum loan-to-value limit. HDB’s financing comparison
Can renovation or HIP give the flat a fresh lease?
Renovation and HIP address the home’s condition. Assess the lease separately from the works completed, and check the flat’s recorded lease before making an offer. A completed upgrading programme should not be used to assume a new lease commencement date. HDB’s HIP overview · Checking the lease
What should I obtain before committing to an older HDB flat?
Obtain a valid HFE letter before the seller grants the Option to Purchase. Check usable CPF, the actual flat lease and the financing available for that address. If borrowing from a bank, obtain its valid Letter of Offer before exercising the option. Budget for renovation and moving before agreeing on a price. HDB’s purchase process
Discuss an older HDB flat on your shortlist
Send me the block, flat type, approximate size and floor range you are considering. I can help compare recorded sales and the viewing questions to ask before you settle on a budget. WhatsApp Jim Tan.
If you are moving from a condo, read Can You Buy an HDB Resale Flat Before Selling Your Condo? alongside this guide. It covers the purchase sequence and the separate private-property disposal rules.
